Home insurance · Chandler, AZ
Insurance for your Arizona home, from roof to pool.
Tell us about the house and a KGB Insurance agent calls you back. We review the roof, the pool and your belongings with you, then quote your home.
Get my home quote Call (480) 545-8877- 4.8 from 86 Google reviews
- Hablamos español
- Mon–Fri 8–6 · Sat 8–noon
 ★★★★★Google review
“Excellent service; they always answer calls and provide courteous, friendly service. Highly recommended.”
Gonzalo MorenoYour quote starts with a review of your home.
We go over your dwelling limit, your personal property limit and your liability limit with you, in English or Spanish.
Have your current declarations page handy, or your closing date if you’re buying. We’ll go through it line by line, show you what you carry today and tell you plainly what we’d change.
What we check on every home
- Your dwelling limit, measured against what it would cost to rebuild today, not what you paid.
- Your roof: its age, its material and how a roof claim would be paid.
- Your deductible: what you’d pay first on a claim, set at an amount you’re comfortable with.
- Your liability, especially if you have a pool or a dog.
- Proof of insurance for your lender, if you’re buying.
“A minor issue came up on my home policy review, Barb got on it, reminded me (a couple of times) and got it successfully resolved. The definition of customer service.”
David Girle, Google reviewHave your declarations page handy
One short call gets you real numbers. Or email us a photo of it if that’s easier.
- 4.8★86 Google reviews
- 3,000+Arizona customers
- Closing on a home?Binder and declarations page for your lender
- Serving all of ArizonaBy phone, email or online
Coverage at a glance
What does home insurance cover in Arizona?
A homeowners policy has three main parts: dwelling for the house, personal property for what’s inside, and liability if someone is hurt and you’re responsible. What each pays depends on your policy’s terms, limits and exclusions.
 1Dwelling 2Belongings 3Liability 4Auto
- 1
Dwelling
The house itself: roof, walls, floors and built-ins like cabinets and the A/C. What it pays after storm damage to the roof depends on your policy’s terms, limits and exclusions.
- 2
Personal property
Your belongings, such as the sofa, the TV, your clothes and the bikes in the garage. We help you set a limit based on what it would cost to replace what you own.
- 3
Personal liability
If a guest is hurt at your home and you’re responsible, liability helps pay their medical bills and your legal costs, up to your limits.
- 4
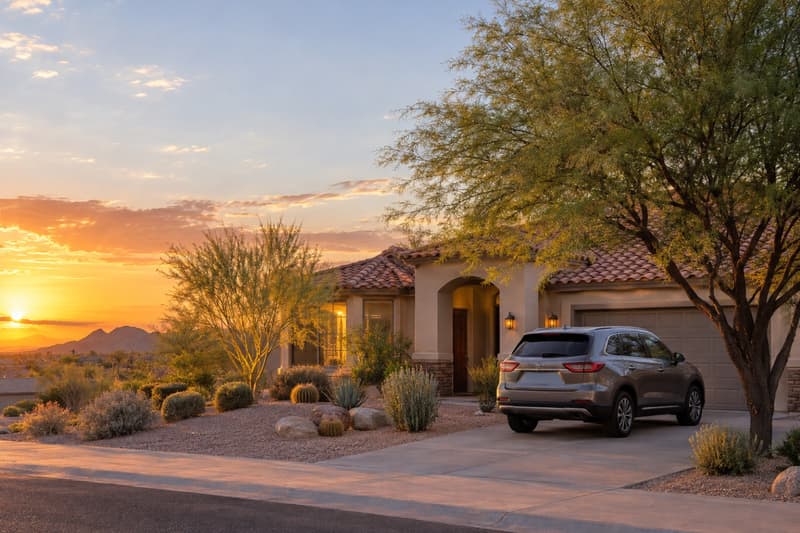
And the SUV in the driveway?
That’s auto. Insure both with KGB Insurance: one review of both policies and one number, (480) 545-8877, for questions. How the bundle works
Monsoon season
Monsoon wind, hail and your roof.
Get a home quote before storm season, and we’ll check your wind and hail deductible and how your policy pays for a roof claim.
Get my home quote Call (480) 545-8877-
Wind and hail
Whether storm damage is paid depends on your policy’s terms, limits and exclusions. Some policies set a separate deductible for wind and hail, so we check yours.
-
Your roof
Desert sun ages every roof: tile, shingle or foam. An older roof can be paid differently on a claim, so we read that part of your policy with you.
-
A review before the season
Send us your declarations page before monsoon season. We’ll read the wind, hail and roof sections with you, so you know your deductible before a storm, not after.
Arizona homes
Six Arizona home details to check.
Tell us about the first five when we quote your home. The sixth is a step you can take today.
-
Pools and backyard guests
A pool adds injury risk for your guests. We check your liability limit with you and can quote an umbrella policy for liability above it.
-
Summer heat and water damage
Heat is hard on pipes, water heaters and A/C lines. A sudden burst and a slow leak or wear can be treated differently, depending on your policy’s terms, limits and exclusions. We’ll show you how yours reads.
-
Wildfire and the cost to rebuild
Near the foothills or the desert edge? Your dwelling limit matters most in a total loss, so we check it against today’s building costs.
-
Block walls, casitas and sheds
Structures not attached to the house can have their own limit on your policy. We’ll ask about the wall, the casita and the shed when we set that limit.
-
Jewelry and valuables
Rings, watches and collections can have lower limits inside a standard policy. Ask us about listing high-value pieces separately on your policy.
-
A quick home inventory
Walk each room with your phone’s camera, open the closets and drawers, and save the video somewhere besides your phone. If you ever file a claim, it helps show what you owned.
Buying a home?
Closing soon? We’ll send your lender proof of insurance.
We work with a large network of mortgage lenders. Tell us your closing date and we’ll send your binder and declarations page to your lender.
Start a home quote Call (480) 545-8877 For lenders & home buyersHow it works
Your home quote in three steps.
- 1
Tell us about the home
Use the quote form, or call us with your ZIP code.
- 2
Walk through it together
We go over your current declarations page by phone, by email or in our office, and explain each coverage and limit, in English or Spanish.
- 3
Choose and start coverage
You choose your coverage and a start date. We set up the policy and send proof of insurance to your lender if you’re buying.
Renewing soon or closing on a home?
Start your home quote now, or call Mon–Fri 8–6 or Sat 8–noon.
Get my home quoteCall (480) 545-8877Google reviews
Arizona customers, in their own words.
4.8 ★★★★★4.8 / 5 average · 86 reviews
78 of them are five stars
Read more reviews ★★★★★Google reviewExcellent customer service!! Very happy with the outcome of the bundle insurance we purchased.
NVNely Valero ★★★★★Google reviewPeople here are great… The folks here fought & got this resolved. Thanks
MMMike Mckinnon ★★★★★Google reviewOutstanding service from start to finish. My agent was knowledgeable, patient, and truly cared about finding the right policy for me. They explained everything clearly and made sure I felt confident in my decisions. I appreciate the responsiveness and professionalism—definitely a 5-star experience!
KKKneo Knight ★★★★★Google reviewKittelson-Gonzalez and team did a great job. I’m very happy with the results. … They worked around my work schedule to keep me up to date on status of request while quote was in process. Excellent team work and customer service!
MSM S ★★★★★Google reviewA minor issue came up on my home policy review, Barb got on it, reminded me (a couple of times) and got it successfully resolved. The definition of customer service.
DGDavid GirleQuestions
Home insurance questions, answered.
What do I need for a home quote?Your address or ZIP code, whether you own or are buying, and your current declarations page if you have one. If you know your roof’s age and material, that helps too. Buying? Tell us your closing date.
Does home insurance cover monsoon damage?It depends on your policy’s terms, limits and exclusions. On your policy, we check how wind and hail damage to the roof and the house is handled, and whether there’s a separate wind and hail deductible. Flooding from rising water is different: FEMA’s FloodSmart.gov notes that most homeowners insurance does not cover flood damage, which takes a separate flood policy. Call us or start a quote before storm season to go through yours.
How much dwelling coverage do I need?Enough to rebuild your home at today’s costs. The Insurance Information Institute (iii.org) makes the same point: the price you paid, or the market price, can be more or less than the cost to rebuild, and the land isn’t part of a rebuilding estimate. We’ll compare your dwelling limit with today’s cost to rebuild when we quote.
I’m closing on a home. Can you send proof of insurance to my lender?Yes. We work with a large network of mortgage lenders and can get your binder and declarations page to your lender quickly. Start the quote form or call, and tell us your closing date when we talk.
Can you quote my home and my car at the same time?Yes. Choose “Home + auto” on the quote form, or tell us when you call. We quote both and show you the home and auto policies with and without the bundle, so you can compare. Bundling can qualify you for a multi-policy discount, subject to terms, eligibility and availability.
What’s replacement cost vs. actual cash value in home insurance?They are two ways a policy can pay for your belongings. The Insurance Information Institute (iii.org) explains that actual cash value pays less for older items than you paid for them new, while replacement cost pays to replace them. Which option you can choose, and what it pays, depends on your policy’s terms, limits and exclusions and is subject to eligibility and availability. Ask us to walk you through both on your quote.
Read the guide: Arizona monsoon damage: how home insurance treats wind, hail and flood
Related coverage
Other policies our office quotes alongside home.
- Auto + HomeOne agent for both
- AutoEvery car and driver
- UmbrellaLiability above home and auto
- Not sure what you need?Call (480) 545-8877 with what you own or drive, and we’ll tell you which policy fits.
Open Mon–Fri 8–6 · Sat 8–noon
Ready for a second look at your home policy?
Call or email us with your declarations page. We’ll tell you plainly what you have and what we’d change.
Get my home quote Call (480) 545-8877